

Deductible reduction at specified ages: AIA, AXA and FWD terms
On this page
A deductible-reduction option is not automatic, and application windows differ. These three specified policy versions each offer a once-per-lifetime option without fresh underwriting or evidence of insurability, with different ages, deadlines and coverage-duration conditions.
Sources checked: 23 September 2026. This is a snapshot of the specified versions, not a market-wide survey.
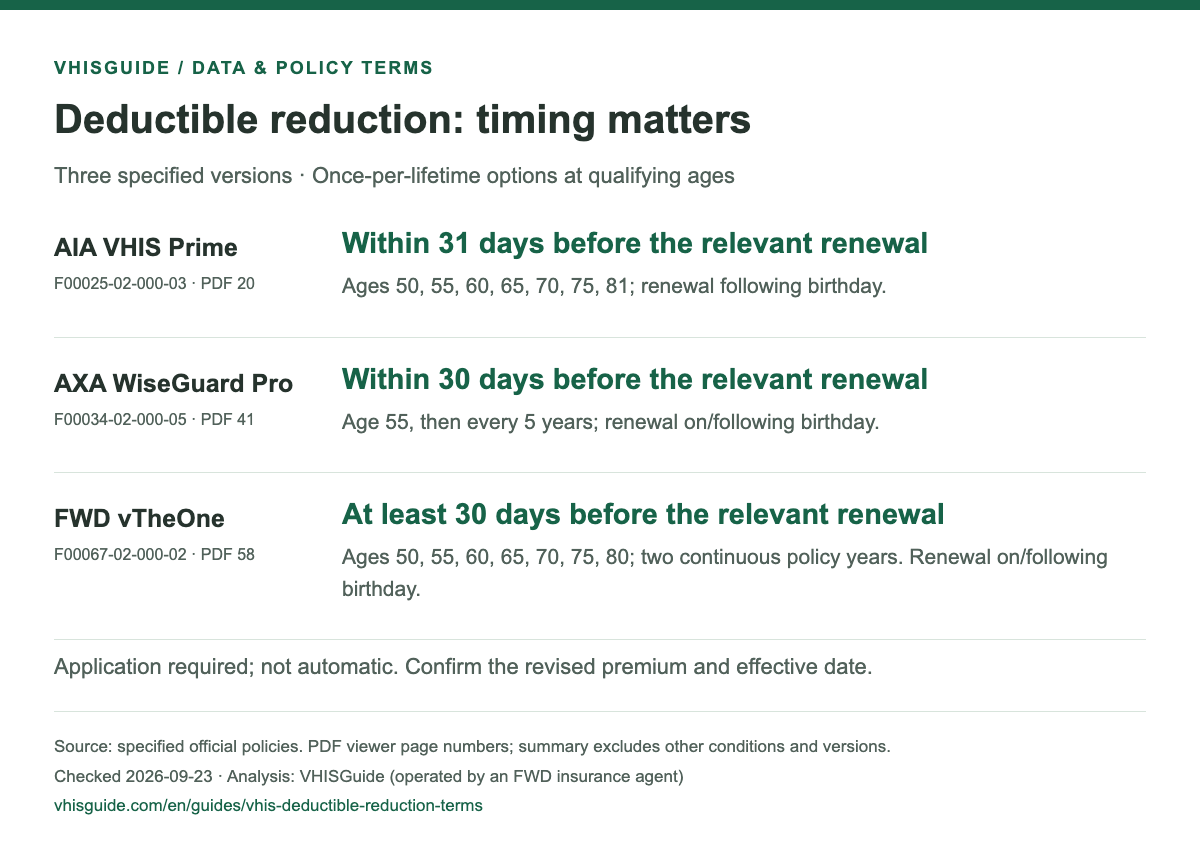
Three policies, compared
| Plan / family | Ages | Application timing | Other conditions |
|---|---|---|---|
| AIA VHIS Prime Scheme · F00025 | 50、55、60、65、70、75、81 | Within 31 days before renewal following the birthday | Once per lifetime; zero-deductible option guaranteed |
| AXA WiseGuard Pro · F00034 | 55 and every fifth birthday thereafter | Within 30 days before renewal on/following the qualifying birthday | Once per lifetime; cancel or reduce the deductible |
| FWD vTheOne Medical Plan · F00067 | 50、55、60、65、70、75、80 | At least 30 days before renewal on/following the qualifying birthday | Once per lifetime; two continuous policy years of cover |
“Within 30 days” is not “at least 30 days before”
The specified AXA option uses a window within 30 days before the relevant renewal. The specified FWD option requires at least 30 days’ notice. AIA uses 31 days and lists age 81 as its final qualifying age. Confirm which renewal follows the qualifying birthday with the insurer; never substitute another plan’s deadline.
No fresh underwriting does not mean an unchanged premium
Ask the insurer to confirm the revised premium and effective date. The reviewed AIA clause explicitly recalculates premiums using age, risk-class rates and accepted loadings at the relevant renewal. This table does not address ordinary applications at other ages, switching policies, other versions or individual endorsements.
Source locations and versions
- AIA VHIS Prime Scheme · F00025-02-000-03 · PDF 20
- AXA WiseGuard Pro · F00034-02-000-05 · PDF 41
- FWD vTheOne Medical Plan · F00067-02-000-02 · PDF 58
Page numbers refer to the PDF viewer, not necessarily the printed numbering. The table summarises the source clauses and is not the full policy wording.
Back to the deductible guide · Compare deductible and premium differences
Download and cite
You may share our original chart with its full title, scope, date and VHISGuide credit, linking to this article. Do not present the figures as a personal quote. Rights in official source documents remain with their owners.
Open PNG chart to save and share · Download sources and calculations (JSON)
VHISGuide is operated by an FWD insurance agent. This is general analysis, not personal insurance or claims advice. Official URLs may later serve revised files; check versions and effective dates.