

What does a higher deductible save? FWD vPrime Signature Standard
On this page
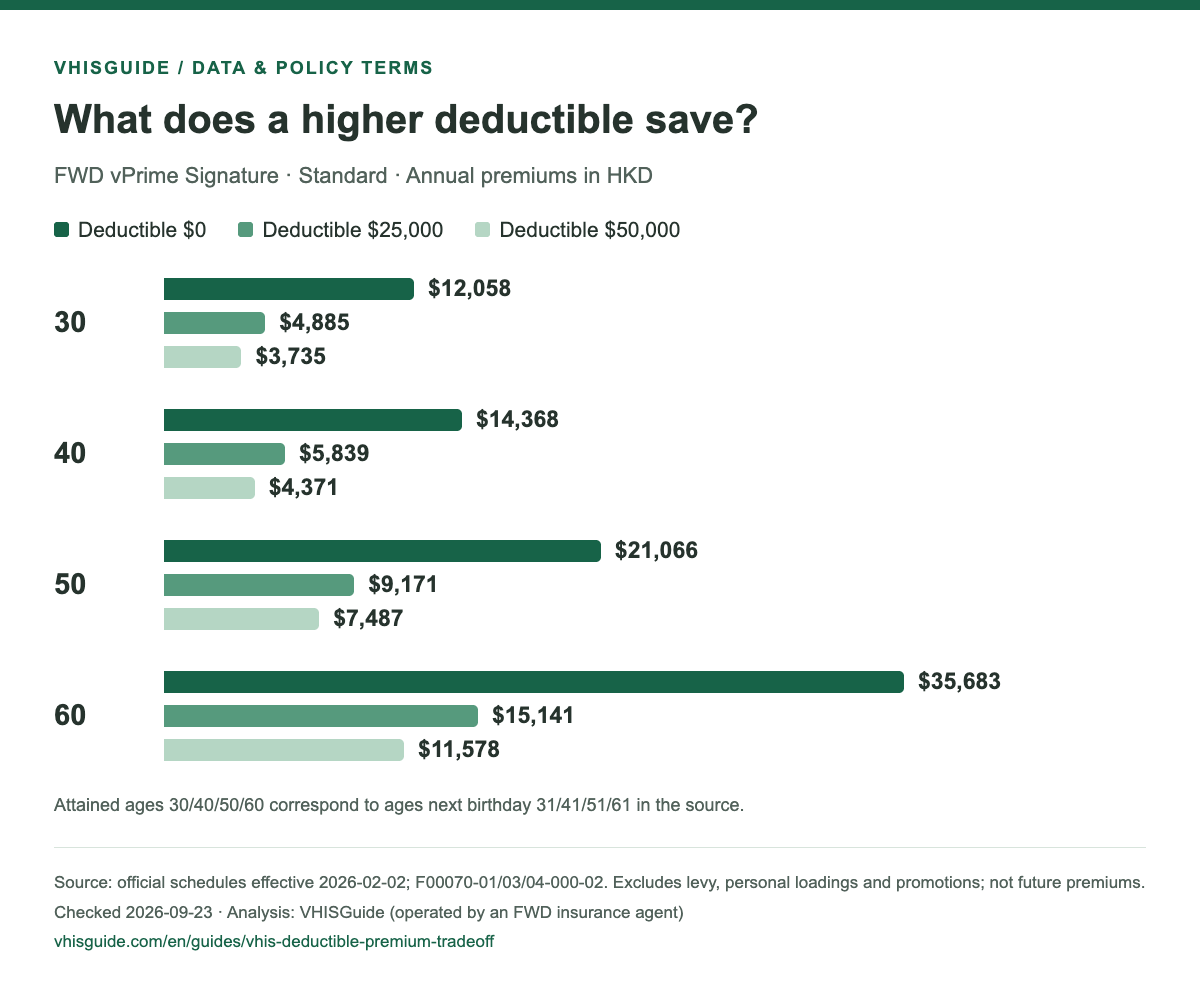
Within the same benefit tier, a higher deductible can mean a lower standard premium and a larger cash reserve requirement. At attained age 30 (age next birthday 31), the FWD vPrime Signature Standard options with HK$0 and HK$25,000 annual deductibles differ by HK$7,173 a year. That difference alone does not determine suitability.
Sources checked: 23 September 2026. This is a snapshot of the specified versions, not a market-wide survey.
Match the comparison conditions
We select three HKD Standard-tier options of FWD vPrime Signature: certifications F00070-01/03/04-000-02, with annual deductibles of HK$0, HK$25,000 and HK$50,000. The annual schedules effective 2 February 2026 use the same rates for men and women. The official schedules use age next birthday; this article and the comparison tool use attained age. Ages 30, 40, 50 and 60 here correspond to 31, 41, 51 and 61 on the PDFs. These are not all the deductible options available.
Amounts exclude levy, individual loadings and promotions. This compares options within one family; it is not a market ranking or a promise of unchanged renewal premiums.
| Attained age | Premium: $0 deductible | Premium: $25,000 deductible | Premium: $50,000 deductible |
|---|---|---|---|
| 30 | 12,058 | 4,885 | 3,735 |
| 40 | 14,368 | 5,839 | 4,371 |
| 50 | 21,066 | 9,171 | 7,487 |
| 60 | 35,683 | 15,141 | 11,578 |
All amounts are HKD per year.
Annual savings and cash exposure
| Age | Annual deductible | Annual saving vs $0 | Premium reduction | Constant-saving years |
|---|---|---|---|---|
| 30 | 25,000 | 7,173 | 59.5% | 3.49 |
| 30 | 50,000 | 8,323 | 69.0% | 6.01 |
| 40 | 25,000 | 8,529 | 59.4% | 2.93 |
| 40 | 50,000 | 9,997 | 69.6% | 5.00 |
| 50 | 25,000 | 11,895 | 56.5% | 2.10 |
| 50 | 50,000 | 13,579 | 64.5% | 3.68 |
| 60 | 25,000 | 20,542 | 57.6% | 1.22 |
| 60 | 50,000 | 24,105 | 67.6% | 2.07 |
Method: annual saving = zero-deductible premium minus selected premium; reduction = saving divided by zero-deductible premium; constant-saving years = deductible difference divided by annual saving. For example, HK$25,000 ÷ HK$7,173 ≈ 3.49 years.
This is not a break-even period. It holds one year’s premium difference constant, excluding ageing, repricing, interest, claims and employer cover. The deductible applies by policy year, not once in a lifetime; claims in successive years can expose you to it repeatedly.
Using this comparison with employer cover
Check actual employer-policy payments and how the personal policy treats other insurance payments before choosing a deductible. Do not simply subtract the employer policy limit. This premium study does not calculate coordination of claims between policies. Consider affordability after leaving employment or retiring.
Open these three options and change your age · Employer cover and deductible guide
Official sources and reproducible data
- Deductible HK$0:F00070-01-000-02
- Deductible HK$25,000:F00070-03-000-02
- Deductible HK$50,000:F00070-04-000-02
PDF page 1 lists premiums; page 2 contains the effective date and renewal notes.
Download premium and calculation CSV
Download and cite
You may share our original chart with its full title, scope, date and VHISGuide credit, linking to this article. Do not present the figures as a personal quote. Rights in official source documents remain with their owners.
Open PNG chart to save and share · Download sources and calculations (JSON)
VHISGuide is operated by an FWD insurance agent. This is general analysis, not personal insurance or claims advice. Official URLs may later serve revised files; check versions and effective dates.